Quick Answer
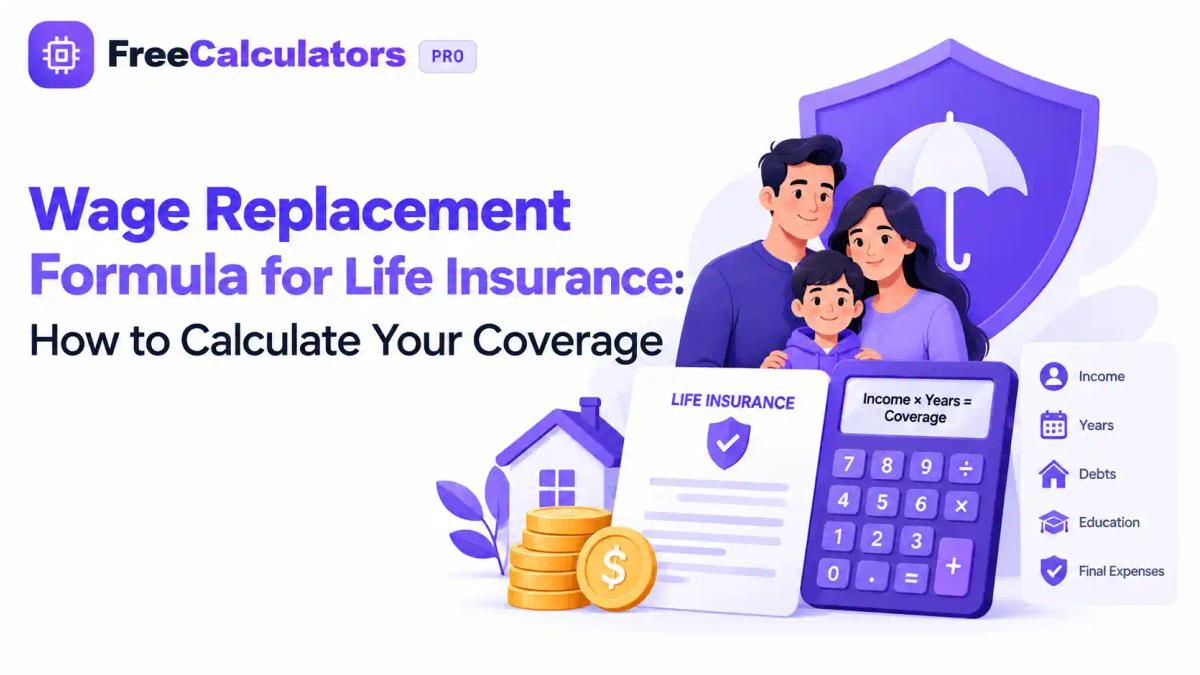
The wage replacement formula for life insurance estimates coverage by multiplying the annual income you want to replace by the number of years your dependents will need financial support. The basic equation is: Income Replacement Need = Annual Income × Years of Replacement. This gives a starting figure, which can then be adjusted for debts, mortgage, education costs, and existing coverage.
Introduction
Figuring out how much life insurance you actually need can feel overwhelming, especially when every calculator, agent, and article seems to suggest a different number. That's exactly why tools like the life insurance calculator on FreeCalculators.tools exist — to take a formula that sounds complicated on paper and turn it into a number you can actually use. If you're comparing term versus permanent coverage, the term life insurance calculator and whole life insurance calculator can help you see how the wage replacement number changes depending on the policy type you choose. And if a mortgage is part of your financial picture, pairing your income replacement figure with a reverse mortgage calculator can give you a fuller view of your family's long-term obligations. In this guide, we'll break down the wage replacement formula step by step, walk through real examples, compare it to the popular DIME method, and answer the questions people most often ask about calculating life insurance coverage based on income.
What Is the Wage Replacement Formula for Life Insurance?
The wage replacement formula, also commonly called the income replacement method, is one of the simplest and most widely used ways to estimate life insurance coverage. The idea is straightforward: if something happened to you, your income would stop, but your family's financial needs wouldn't. This formula tries to replace that lost income stream for a set number of years.
Formula:
Income Replacement Need = Annual Income to Replace × Number of Years of Replacement
Example:
$80,000 × 15 years = $1,200,000
This number represents how much coverage would be needed to replace your salary alone — not your total life insurance need, which we'll get into shortly.
Why Income Replacement Matters
For most households, income is the engine that keeps everything running — the mortgage, groceries, childcare, tuition, and savings. When that income disappears unexpectedly, the financial gap can be immediate and severe. This is why the National Association of Insurance Commissioners (NAIC) encourages consumers to think about who depends on their income, how much of the household's earnings they contribute, and whether any employer-provided coverage would be enough to bridge the gap.
Income replacement planning isn't just for high earners with families. Stay-at-home parents, single-income households, and even dual-income couples often underestimate how much financial disruption a lost income can cause — especially when unpaid household labor and childcare costs are factored in.
How the Income Replacement Method Works
Calculating your wage replacement need comes down to three basic questions:
- What annual income needs to be replaced? This is usually your gross salary, though some planners prefer net income for a more conservative estimate.
- How many years should that income be replaced? This depends on your children's ages, your spouse's earning potential, retirement timelines, and other financial obligations.
- What multiplier or number of years fits your situation? Many advisors suggest a 10× income rule, while others recommend 12×, 15×, or even 20× depending on age and family structure.
The 10x Income Rule (and Its Limits)
You've probably heard some version of "buy 10 times your salary in life insurance." It's a quick, memorable shortcut — but it's just that: a shortcut. A 30-year-old with three young children and a mortgage has very different needs than a 55-year-old whose kids are grown and whose mortgage is nearly paid off. The 10x rule can be a helpful starting point, but it shouldn't be treated as a precise, one-size-fits-all formula.
How Many Years of Income Should Life Insurance Replace?
This is one of the most important — and most personal — decisions in the entire calculation. Factors to consider include:
- Your children's current ages and when they'll be financially independent
- Whether your spouse works and how much they earn
- How many years remain until retirement
- Outstanding mortgage or debt timelines
- College or education funding timelines
A parent with a newborn might choose 20+ years of replacement, while someone whose youngest child is about to graduate college might only need 5–7 years.
Income Replacement vs. the DIME Method
While the wage replacement formula focuses purely on income, the DIME method takes a broader approach by adding:
- Debt (excluding mortgage)
- Income replacement
- Mortgage balance
- Education costs
DIME Formula:
Total Coverage Need = Debt + Income Replacement + Mortgage + Education Costs
DIME often produces a higher number than income replacement alone because it accounts for large one-time obligations like paying off a house or funding a college education. If you're weighing which method fits your household, running both numbers side by side — perhaps alongside a college savings calculator or 529 calculator for education costs — can help you see the full picture.
Beyond the Basic Formula: Building a Complete Coverage Estimate
Income replacement is just one piece of a larger life insurance needs analysis. A more complete calculation often looks like this:
Total Coverage Need = Income Replacement + Debts + Mortgage + Education + Final Expenses − Existing Coverage − Available Assets
This is why it's worth checking your current policies — including any employer-sponsored life insurance — before finalizing a number. Many people are surprised to learn their workplace coverage only replaces one or two years of salary, leaving a significant gap.
Worked Examples
Example A — Single Earner, No Children
Annual income: $60,000
Replacement years: 8 (until financial independence)
Income Replacement Need: $480,000
Example B — Married Household With Children
Annual income: $90,000
Replacement years: 18 (until youngest child is independent)
Income Replacement Need: $1,620,000
Example C — Income Plus Mortgage and Debt
Annual income: $75,000 × 15 years = $1,125,000
Remaining mortgage: $250,000
Other debt: $30,000
Total Coverage Need: $1,405,000
Example D — Existing Employer Coverage
Calculated need: $1,200,000
Existing employer life insurance: $150,000
Remaining Coverage Gap: $1,050,000
Should You Adjust for Inflation?
A dollar today won't stretch as far in 15 or 20 years. Some financial planners recommend inflation-adjusting the income figure or choosing a slightly higher multiplier to account for rising costs, especially for longer replacement periods. Others prefer to reassess coverage every few years instead of trying to predict inflation decades in advance — both approaches are reasonable, and the right one depends on how hands-on you want to be with future adjustments.
What Existing Resources Should Reduce Your Number?
Before settling on a final coverage amount, subtract what you already have in place:
- Employer-provided group life insurance
- Existing individual term or whole life policies
- Significant savings or investment accounts
- Social Security survivor benefits, where applicable
This step often meaningfully lowers the additional coverage a household needs to purchase.
Best Free Tools to Calculate Your Coverage
Running these numbers by hand is doable, but a calculator removes the guesswork and lets you test different scenarios quickly. FreeCalculators.tools offers several tools that pair well with wage replacement planning:
- Life Insurance Calculator — estimate your overall coverage need
- Term Life Insurance Calculator — model coverage for a fixed policy term
- Whole Life Insurance Calculator — compare permanent coverage options
- Reverse Mortgage Calculator — factor in mortgage-related obligations
- Commercial Loan Calculator — useful for self-employed business owners estimating debt
- FIRE Calculator — see how coverage needs shift as you approach financial independence
- College Savings Calculator and 529 Calculator — plan for education costs that may factor into your DIME calculation
- Homeowners Insurance Calculator — round out your overall household protection picture
You can browse the full library of tools on the FreeCalculators.tools homepage or check out more insurance-planning content on the blog.
Common Mistakes People Make
- Using only the 10x rule without adjusting for personal circumstances. A flat multiplier ignores debt, dependents, and timeline differences.
- Forgetting to subtract existing coverage. This leads to overbuying and paying unnecessary premiums.
- Ignoring inflation over long replacement periods. A 20-year estimate in today's dollars may fall short later.
- Overlooking a stay-at-home parent's economic value. Childcare and household management have real financial replacement costs.
- Confusing gross and net income. Mixing the two inconsistently skews the final number.
- Treating income replacement as the entire coverage need. It's one component of a broader calculation that should include debt, mortgage, and education costs.
Future Trends in Life Insurance Planning
As financial planning tools become more sophisticated, expect to see:
- AI-assisted life insurance calculators that factor in real-time inflation data, investment returns, and personalized life events
- Dynamic coverage recommendations that update automatically as income, debt, or family size changes
- Greater integration between insurance and retirement planning tools, giving households a single dashboard for long-term financial security
- Increased consumer education driven by government resources and organizations like the NAIC, helping people move beyond generic rules of thumb
FAQs
What is the wage replacement formula for life insurance?
It's a method that estimates coverage by multiplying the annual income you want to replace by the number of years your dependents will need financial support. It's often expressed as Annual Income × Years of Replacement.
How is income replacement different from the DIME method?
Income replacement focuses only on lost salary, while DIME adds debt, mortgage, and education costs on top of income replacement, typically producing a higher coverage figure.
Is 10 times my income enough life insurance?
It can be a reasonable starting point, but it doesn't account for personal factors like debt, number of dependents, or years until retirement. Many households need more or less than the 10x shortcut suggests.
Should I use gross or net income for the calculation?
Either can work, but consistency matters. Gross income is more common and generally produces a more conservative (higher) estimate.
How many years of income should life insurance replace?
This depends on your dependents' ages, your spouse's income, and your retirement timeline. Common ranges run from 10 to 20+ years.
Does income replacement include Social Security survivor benefits?
Not automatically. Survivor benefits can be factored in separately to reduce the additional coverage needed, but they're not part of the base formula.
Should existing employer life insurance be subtracted from my total?
Yes. Any existing coverage, including workplace policies, should generally be subtracted from your calculated need to find your true coverage gap.
Can a life insurance calculator replace a full needs analysis?
A calculator is a strong starting point and gives you a realistic ballpark figure, but a full needs analysis with a financial advisor can help fine-tune the number based on your complete financial picture.
Does inflation affect income replacement calculations?
Yes. Over long replacement periods, inflation can erode purchasing power, which is why some planners recommend periodic reassessment or a slightly higher initial coverage amount.
Key Takeaways
- The wage replacement formula is: Annual Income × Years of Replacement.
- It's a starting point, not a complete life insurance needs calculation.
- The DIME method adds debt, mortgage, and education costs for a fuller picture.
- Existing coverage and savings should be subtracted from your final number.
- The number of replacement years depends on dependents' ages and retirement timeline.
- Inflation can meaningfully affect long-term replacement calculations.
- Free online calculators make it easy to test different scenarios quickly.
Expert Summary
The wage replacement formula offers a simple, transparent way to estimate life insurance coverage: multiply the income you want to protect by the number of years it needs replacing. While useful as a foundation, it works best alongside a broader needs analysis that accounts for debt, mortgage balances, education costs, and existing coverage. Households should treat multipliers like 10x or 15x as flexible guidelines rather than fixed rules, adjusting for family structure, retirement timing, and inflation. Reassessing coverage periodically — especially after major life events — helps ensure the policy in place continues to reflect real financial needs.
Conclusion
Life insurance planning doesn't have to be intimidating once you break it down into a clear formula. Starting with your annual income and a realistic number of replacement years gives you a solid foundation, and layering in debts, mortgage, education costs, and existing coverage rounds out the full picture. From there, the right amount of coverage becomes a much clearer, more confident decision.
Call to Action
Ready to put these numbers to work for your own family? Start with the Life Insurance Calculator to get a personalized estimate in minutes, then explore the Term Life Insurance Calculator, Whole Life Insurance Calculator, Reverse Mortgage Calculator, Commercial Loan Calculator, FIRE Calculator, College Savings Calculator, 529 Calculator, Homeowners Insurance Calculator, Auto Insurance Calculator, and Car Insurance Calculator to build a complete financial protection plan. You can browse every free tool on the FreeCalculators.tools homepage, learn more about the platform on the About Us page, check out the full range of offerings on the Services page, or read more insurance and planning guides on the blog, including How Much Term Life Insurance Do You Need in 2026. If you'd rather talk through your numbers with someone directly, don't wait — Book a Seat with our team today and take the guesswork out of protecting your family's financial future.