Quick Answer
20-year term life insurance provides life insurance coverage for a fixed 20-year period in exchange for a fixed premium. If you pass away while the policy is active, your beneficiaries typically receive a tax-free death benefit. It's one of the most affordable and popular ways to protect your family's income, mortgage, and future expenses.
Introduction
Buying life insurance can feel overwhelming, especially when you're trying to figure out how much coverage you actually need and how long that coverage should last. For millions of Americans, 20-year term life insurance hits the sweet spot — it's affordable, straightforward, and lines up neatly with common financial milestones like paying off a mortgage or getting kids through college. Before you start comparing quotes, it helps to run your numbers through a life insurance calculator so you know roughly how much coverage fits your situation. If you're weighing term against permanent coverage, the whole life insurance calculator and the dedicated term life insurance calculator can help you compare premiums side by side. And because insurance is only one piece of a bigger financial picture, tools like FreeCalculators.tools are a genuinely useful starting point for anyone trying to plan coverage, savings, and debt payoff all in one place. This guide walks through everything you need to know — what a 20-year term policy actually covers, how pricing works, how to buy one step by step, and the mistakes to avoid along the way.
What Is 20-Year Term Life Insurance?
20-year term life insurance is a type of level term life insurance that guarantees a fixed death benefit and a fixed premium for exactly 20 years. As long as you keep paying your premium payments, the policy stays active (in force) for that entire coverage period.
Unlike whole life insurance or universal life insurance, term life insurance doesn't build cash value — it's pure protection. That's part of why it's so much more affordable than permanent life insurance for the same coverage amount.
Key features of a 20-year term life policy:
- Fixed premium for the full 20-year policy term
- Level death benefit that doesn't decrease over time
- No cash value or investment component
- Coverage ends at the end of the term unless renewed or converted
How Does a 20-Year Term Life Insurance Policy Work?
Here's the mechanism in plain English: you apply for coverage, go through underwriting (more on that below), and once approved, you start paying premiums — usually monthly or annually. In exchange, the insurer promises to pay your named beneficiary the policy's death benefit if you die at any point during the 20-year term.
If you outlive the term, the coverage simply ends. There's no payout, no refund (unless you bought a return-of-premium rider), and no further obligation from either side — unless you choose to renew or convert the policy before it expires.
How Much 20-Year Term Life Insurance Do You Need?
This is the question most people get wrong. A common rule of thumb is 10–15 times your annual income, but a more accurate approach factors in your specific obligations:
- Outstanding mortgage balance
- Personal debt (credit cards, auto loans, student loans)
- Number of dependents and their ages
- Future college expenses
- Income replacement needs for your spouse or partner
- Existing savings and emergency funds
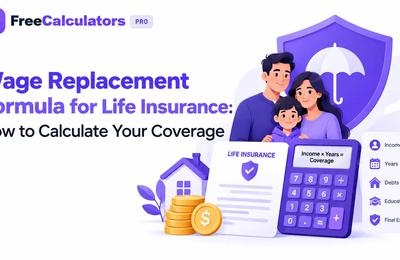
Many financial professionals use the DIME formula — Debt, Income, Mortgage, Education — to estimate a reasonable coverage amount. Add up your total debt, years of income you want to replace, remaining mortgage balance, and future education costs, and you'll get a realistic human life value estimate.
Rather than doing this math by hand, running your numbers through a life insurance calculator gives you a quick, personalized estimate in minutes. If college is part of the equation, the college savings calculator and 529 calculator can help you see how much of that future expense your policy should actually cover.
How Much Does 20-Year Term Life Insurance Cost?
Term life insurance cost varies significantly based on individual risk factors, but as a general benchmark, a healthy 30-year-old non-smoker can often get $500,000 of 20-year term coverage for well under $30/month. Premiums rise with age, health issues, and coverage amount.
What Affects 20-Year Term Life Insurance Rates?
Insurers use an underwriting process to assess risk and assign a risk classification. The main factors include:
- Age — younger applicants generally pay less
- Health — blood pressure, cholesterol, weight, and pre-existing conditions all matter
- Tobacco use — smokers typically pay 2–3x more than non-smokers
- Gender — women statistically pay slightly less due to longer life expectancy
- Coverage amount — higher death benefits mean higher premiums
- Occupation and hobbies — high-risk jobs or activities (like piloting or skydiving) can raise rates
- Family medical history — a history of hereditary conditions can affect your underwriting class
If you want to see how these variables shift your estimated premium before talking to an agent, the term life insurance calculator is a fast way to model different scenarios.
How to Buy 20-Year Term Life Insurance: Step by Step
- Determine your coverage needs. Use the DIME formula or a life insurance calculator to land on a realistic number.
- Choose the right policy term. Consider how long your financial obligations — mortgage, dependents, debt — will actually last.
- Compare insurers and quotes. Look at multiple carriers rather than settling for the first quote you receive.
- Review eligibility and underwriting requirements. Understand whether you'll need a medical exam or qualify for no-exam life insurance.
- Complete the application. Provide accurate health, lifestyle, and financial information.
- Complete any required medical exam. This typically includes blood pressure, height/weight, and a blood or urine sample.
- Review the final policy. Check the death benefit, premium, riders, and exclusions carefully.
- Pay the required premium and select or confirm your beneficiary designation.
How to Compare 20-Year Term Life Insurance Quotes
When comparing quotes, don't just look at the monthly premium. Also compare:
- Financial strength ratings of the insurer
- Conversion privileges (can you convert to whole life insurance or universal life insurance later?)
- Available riders (waiver of premium, accidental death benefit, critical illness rider)
- Claims-paying reputation and settlement ratio
- Whether the policy is guaranteed renewable
What to Look for in a 20-Year Term Life Insurance Policy
A strong policy should offer a level death benefit, a fixed premium for the full term, clear conversion options, and transparent language around exclusions (such as suicide clauses in the first two years). Always confirm the insurer is licensed in your state and check ratings through resources like the National Association of Insurance Commissioners (NAIC).
20-Year vs. 30-Year Term Life Insurance
| Factor | 20-Year Term | 30-Year Term |
| Coverage period | 20 years | 30 years |
| Typical purpose | Mid-term financial protection | Longer financial protection |
| Premium | Generally lower | Generally higher |
| Best for | Specific financial obligations expected to end sooner | Obligations extending further into the future |
20-year term may make sense when:
- Your mortgage or major debt is expected to be paid off within 20 years
- Your children will likely be financially independent adults by then
- You want the lowest possible premium for solid, mid-term protection
30-year term may make sense when:
- You have young children who will depend on you for decades
- Your mortgage term extends well beyond 20 years
- You want long-term income replacement locked in early, while premiums are lower
Do You Need a Medical Exam?
Traditional term life insurance usually requires a medical exam — blood pressure, blood and urine samples, height, and weight. However, no-exam life insurance has become increasingly common, especially for applicants under 50 seeking moderate coverage amounts. No-exam policies use existing health records, prescription history, and simplified underwriting instead. They're often quicker but may come with slightly higher premiums than fully underwritten policies.
What Happens When a 20-Year Term Policy Ends?
When your 20-year term expires, coverage simply ends — there's no payout if you're still alive. At that point, you generally have three options: let the policy lapse, apply for a new policy (at a higher premium due to your current age), or renew/convert if your policy included that provision.
Can You Renew or Convert a 20-Year Term Policy?
Many policies are guaranteed renewable, meaning you can extend coverage after the term ends — usually as annual renewable term, at a significantly higher premium. Convertible term life insurance lets you convert some or all of your coverage to whole life insurance or universal life insurance without a new medical exam, which can be valuable if your health has changed. Reviewing your coverage periodically — and re-running the numbers through a life insurance calculator — helps you decide whether renewal, conversion, or a fresh policy makes more sense as your life changes.
Best Free Tools to Plan Your Life Insurance Coverage
Before you buy — or even request a quote — it's worth running your numbers through a few free planning tools:
- Life Insurance Calculator — Estimate the coverage amount that fits your income, debts, and family needs.
- Term Life Insurance Calculator — Compare premiums across different term lengths and coverage amounts.
- Whole Life Insurance Calculator — See how permanent coverage costs compare to term.
- College Savings Calculator and 529 Calculator — Factor future education costs into your coverage amount.
- Reverse Mortgage Calculator — Useful if mortgage protection is part of your long-term planning.
- FIRE Calculator — Helpful for aligning life insurance with broader retirement planning and financial independence goals.
FreeCalculators.tools also offers a full library of insurance calculators, including car insurance and homeowners insurance tools, so you can plan your entire insurance portfolio in one place.
Common Mistakes to Avoid When Buying Term Life Insurance
- Underestimating coverage needs by ignoring inflation, future debts, or education costs
- Choosing the cheapest quote without checking the insurer's financial strength or claims record
- Skipping the medical exam prep (fasting, hydration) which can affect your health classification
- Forgetting to name a beneficiary or failing to update it after major life events
- Assuming term life insurance builds cash value — it doesn't; that's a whole life insurance feature
- Not reviewing conversion options before your term ends
- Buying based on term length alone without matching it to actual financial obligations
Practical Examples
Example 1: A 32-year-old parent with a $300,000 mortgage, two young children, and a goal of covering 15 years of income replacement might land on roughly $750,000–$1,000,000 in coverage using the DIME formula.
Example 2: A 45-year-old with a mortgage that will be paid off in 12 years and no dependents might reasonably choose a smaller death benefit and a shorter term, since major financial obligations are set to decline.
Example 3: A dual-income household with a 25-year mortgage might find that a 30-year term better matches their obligations than a 20-year term, even though the premium is somewhat higher.
Future Trends in Term Life Insurance
The buying process is changing quickly. Expect to see more:
- AI-assisted life insurance shopping and personalized pricing
- Accelerated and digital underwriting using electronic health records instead of traditional exams
- Instant-decision life insurance for healthy applicants under certain coverage thresholds
- Online policy management portals that make renewals, conversions, and beneficiary updates simpler
Frequently Asked Questions
What is 20-year term life insurance?
It's a life insurance policy that provides a fixed death benefit for 20 years in exchange for a fixed premium. If the insured dies during the term, beneficiaries generally receive the payout tax-free.
How much does 20-year term life insurance cost?
Cost depends on age, health, coverage amount, and tobacco use. A healthy 30-year-old might pay under $30/month for $500,000 in coverage, while older or higher-risk applicants pay more.
How much coverage do I need?
A common guideline is 10–15 times your annual income, adjusted for debt, mortgage balance, dependents, and future expenses like college. A life insurance calculator can help refine this.
Is 20-year term life insurance better than 30-year?
It depends on your obligations. Choose 20-year term if major debts and dependent needs will likely end within two decades; choose 30-year if they'll extend longer.
Do I need a medical exam to buy term life insurance?
Not always. No-exam term life insurance is available for many applicants, though it may cost more than fully underwritten policies with a medical exam.
Can I renew my term life insurance after 20 years?
Many policies are guaranteed renewable, though premiums increase significantly at renewal since they're based on your age at that time.
Can I convert term life insurance to permanent coverage?
Yes, if your policy includes a conversion privilege. This lets you switch to whole life insurance or universal life insurance without new medical underwriting.
What happens if I outlive my 20-year term policy?
Coverage simply ends with no payout, unless you added a return-of-premium rider or choose to renew/convert before expiration.
Is term life insurance tax deductible?
Generally, individual term life insurance premiums are not tax-deductible, and death benefits are typically received income-tax-free by beneficiaries.
Can I have more than one term life insurance policy?
Yes, many people layer policies (a strategy called "laddering") to match different coverage amounts to different financial obligations over time.
Key Takeaways
- 20-year term life insurance offers a fixed death benefit and fixed premium for a 20-year coverage period.
- Coverage needs should be based on income, debt, mortgage, and dependents — not guesswork.
- Premiums depend on age, health, tobacco use, and coverage amount.
- No-exam options exist, but traditional underwriting often results in better rates for healthy applicants.
- 20-year and 30-year terms suit different financial timelines — match the term to your actual obligations.
- Guaranteed renewability and conversion privileges add flexibility as your needs change.
- Comparing quotes across multiple insurers — not just price — leads to better long-term value.
- Free calculators can help you estimate coverage and premiums before you talk to an agent.
Expert Summary
20-year term life insurance remains one of the most cost-effective ways for American families to protect income, mortgage payments, and future expenses during their highest-obligation years. Coverage amounts should be based on a structured approach — such as the DIME formula — rather than rough estimates, and premiums are driven primarily by age, health, and tobacco use. Buyers should compare insurers on financial strength, riders, and conversion options, not price alone. Understanding what happens at policy expiration, and whether renewal or conversion is available, helps ensure long-term protection continues to match evolving financial responsibilities.
Conclusion
Choosing the right term length and coverage amount doesn't have to be complicated once you break it down into a few clear steps: figure out your real financial obligations, compare policies properly, and understand what happens when the term ends. A 20-year term life insurance policy can offer meaningful protection during exactly the years your family needs it most — without the higher cost of permanent coverage.
Call to Action
Ready to get your numbers right before you request a quote? Start with the Life Insurance Calculator to estimate your ideal coverage amount, then compare term options with the Term Life Insurance Calculator and Whole Life Insurance Calculator. If mortgage protection, college costs, or retirement planning are part of your picture, check out the Reverse Mortgage Calculator, College Savings Calculator, 529 Calculator, and FIRE Calculator — all free, all built to help you plan with real numbers instead of guesswork.
Want personalized guidance on top of the numbers? Book a Seat for a free planning consultation and walk through your coverage needs, insurance options, and full financial picture with confidence. While you're at it, explore the full suite of tools — from the Auto Insurance Calculator and Car Insurance Calculator to the Homeowners Insurance Calculator, Commercial Loan Calculator, Business Calculator, AARP Calculator, and Basic Calculator — and read more on our blog, including our related guide on how much term life insurance you need in 2026. Learn more about us, browse our full services, or contact us directly — and visit FreeCalculators.tools anytime you need a free, reliable financial planning tool.