Quick Answer
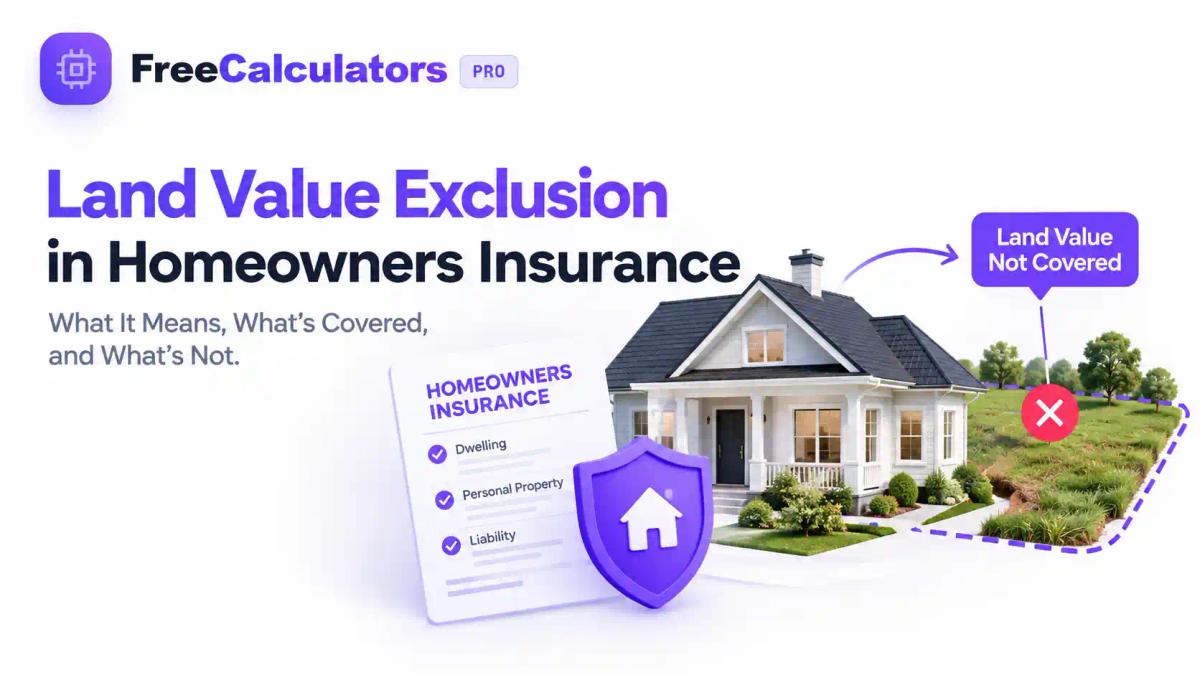
Homeowners insurance generally does not cover the market value of the land your house sits on. Instead, dwelling coverage insures the physical structure — the cost to repair or rebuild it after a covered loss. This is why your policy's coverage limit is often lower than your total property value, since land isn't destroyed by fire, wind, or most other covered perils.
Introduction
If you've ever looked at your homeowners insurance declarations page and wondered why the coverage amount seems lower than what you paid for your house, you're not alone. This confusion almost always comes down to one concept: land value exclusion in homeowners insurance. Your property's total worth includes both the land beneath your home and the structure built on top of it — but insurers are only in the business of insuring the part that can actually be damaged or destroyed.
Before diving into the details, it's worth running the numbers on your own property. Tools like the Homeowners Insurance Calculator on FreeCalculators.tools can help you estimate an appropriate dwelling coverage amount based on your home's characteristics rather than its full market price. If you're also weighing how a mortgage payoff or refinance affects your overall property picture, the Reverse Mortgage Calculator and Commercial Loan Calculator can round out that financial planning. And since insurance decisions often intersect with broader estate and family protection planning, many homeowners also compare options using a Life Insurance Calculator while they're at it. In this guide, we'll break down exactly why land is excluded, how insurers calculate what they do cover, and how to make sure your policy actually protects what matters.
What Is Land Value Exclusion in Homeowners Insurance?
Land value exclusion refers to the standard practice in homeowners insurance policies of not insuring the market value of the land itself — only the structures and covered property built on it. A homeowners policy is designed to pay for repair or reconstruction of your home after a covered event like fire, wind, hail, or theft. Since land can't burn down, blow away, or be stolen, it simply isn't part of what the policy is built to protect.
This is a foundational distinction in entity SEO terms: homeowners insurance connects to dwelling coverage, which connects to replacement cost, which connects to the physical structure. Land, by contrast, belongs to a separate category — real estate value, driven by location, zoning, and market demand — that insurers don't underwrite.
Does Homeowners Insurance Cover Land?
No — homeowners insurance does not cover land. Standard policies, including common HO-3 and HO-5 forms, are structured around Coverage A (Dwelling) and Coverage B (Other Structures), both of which apply to physical buildings, not the ground beneath them. If your home is destroyed, your policy pays to rebuild the structure — not to compensate you for the land's real estate value, which remains yours regardless of what happens to the house.
This is one of the most searched questions in this space, and it's worth repeating plainly: is land covered by homeowners insurance? In virtually all standard cases, the answer is no.
Why Is Land Value Excluded From Homeowners Insurance?
There are a few practical reasons insurers structure policies this way:
- Land isn't a covered peril target. Fire, wind, hail, and most named perils damage structures, not soil.
- Land retains value after a loss. Even after a total loss, the property owner still owns the land and can rebuild or sell it.
- Insuring land would inflate premiums unnecessarily. If insurers had to cover land value, premiums in high-cost real estate markets would be dramatically higher, even though risk to the physical structure hasn't changed.
- Replacement cost, not market value, drives the calculation. Insurers focus on labor and materials needed to rebuild — a cost that has little to do with what the land beneath the home is worth.
Regulatory bodies such as the National Association of Insurance Commissioners (NAIC) and state insurance departments generally reinforce this structure across the industry, which is part of why the exclusion is so consistent from one insurer to the next.
Land Value vs. Home Replacement Cost
This is the single most important distinction in the entire topic, so it's worth spelling out clearly.
| Concept | Driven By | Relevant to Homeowners Insurance? |
| Land value | Location, zoning, market demand | Generally no |
| Dwelling replacement cost | Materials, labor, square footage, local construction rates | Yes |
| Personal property | Belongings inside the home | Often, up to policy limits |
| Landscaping | Plants, trees, outdoor design | Depends on policy/coverage |
| Driveways/walkways | Attached structures | May be covered depending on policy |
Home replacement cost is what it would cost, today, to rebuild your home using similar materials and construction methods. It has nothing to do with what a buyer would pay for your property on the open market — that's where land value, neighborhood demand, and comparable sales come in.
Market Value vs. Replacement Cost
These two figures often diverge significantly, and understanding why helps explain the entire concept of land value exclusion.
- Market value reflects what a buyer would pay for your entire property — house and land combined — influenced by location, school districts, comparable home sales, and local demand.
- Replacement cost reflects what it costs to physically rebuild the structure, based on construction materials, labor rates, and square footage — independent of neighborhood desirability.
In expensive real estate markets, market value can be far higher than replacement cost simply because land is scarce and in demand. In more rural or affordable markets, the gap may be smaller. Either way, your dwelling coverage should track replacement cost, not market value.
What Does Dwelling Coverage Actually Cover?
Dwelling coverage (Coverage A) typically applies to:
- The main structure of your home
- Attached structures like an attached garage
- Built-in fixtures and systems (plumbing, electrical, HVAC)
- Framing, roofing, and foundation repairs after a covered loss
Other structures coverage (Coverage B) typically extends to detached structures like sheds, fences, or a detached garage — again, only the structures themselves, not the ground they sit on.
Homeowners often benefit from checking their coverage against an actual rebuild estimate rather than assuming their purchase price or home appraisal reflects the right number. The Homeowners Insurance Calculator is a useful starting point for that comparison, and for a rough materials-and-labor sanity check on rebuild costs, some homeowners even use a Concrete Calculator as part of estimating foundation or structural rebuild scope.
How Land Value Affects Your Home Insurance Calculation
Even though land isn't insured, it still indirectly shapes your homeowners insurance experience:
- Premiums may be higher in high-land-value areas because of associated risks (wildfire zones, coastal exposure) rather than the land value itself.
- Insurance-to-value ratios are calculated using replacement cost, not your home's total market value — so don't assume your coverage should match your purchase price.
- Underinsurance risk increases when homeowners assume their coverage limit should equal their home's full sale price, including land.
This is exactly where a coinsurance clause can create problems: if your dwelling coverage falls significantly below the actual replacement cost of your home, a claim payout could be reduced, even though the shortfall had nothing to do with land value at all.
Example of Land Value Exclusion
Here's a simple, illustrative example (not a universal formula):
A homeowner's property has a total market value of $600,000. Of that:
- $200,000 reflects the land value
- $400,000 reflects the building/reconstruction cost
In this scenario, the homeowner's dwelling coverage would generally be built around the $400,000 rebuild cost — not the full $600,000 market value. If the home were destroyed in a covered fire, the insurer would pay based on the cost to rebuild a comparable structure, and the homeowner would still own the $200,000 worth of land afterward.
What Happens to the Land After a Total Home Loss?
This is one of the most common and reassuring questions homeowners ask. If a covered event completely destroys a house, the land itself remains the owner's property. Homeowners insurance pays out based on dwelling coverage to rebuild (or, in some cases, to settle a claim in cash), but the land underneath was never at risk of "loss" in the insurance sense — it's still there, and it's still yours. Many homeowners then use their settlement to rebuild on the same lot, which is precisely why insurers don't need to factor land value into the payout.
Does Homeowners Insurance Cover Landscaping and Outdoor Property?
Coverage here varies more than with land itself. Many policies provide limited coverage for landscaping — trees, shrubs, and plants — often capped at a small percentage of dwelling coverage, and usually only for specific named perils like fire or vandalism (not standard wind or disease damage). Driveways, walkways, and fences may fall under other structures coverage, again subject to policy limits and endorsements. As always, checking your specific policy wording and endorsements is the only way to know for certain what's included.
How Much Dwelling Coverage Do You Need?
Rather than defaulting to your home's purchase price or market value, base your dwelling coverage decision on:
- Your home's square footage and physical characteristics
- Local construction material and labor costs
- Special architectural features (custom finishes, additions)
- Your insurer's replacement-cost methodology
- Demolition and debris-removal costs where applicable
Running your numbers through a dedicated Homeowners Insurance Calculator can help you sanity-check whether your current limit is realistic, especially if you haven't updated your policy since construction costs rose in recent years.
Common Mistakes When Calculating Home Insurance Coverage
- Assuming coverage should equal purchase price. Purchase price includes land; dwelling coverage shouldn't.
- Using market value instead of replacement cost. These numbers can diverge significantly, especially in high-demand areas.
- Not updating coverage after renovations. An addition or major remodel increases rebuild cost even if land value hasn't changed.
- Ignoring inflation in construction costs. Materials and labor costs shift yearly; static coverage limits become outdated.
- Overlooking other structures and personal property limits, assuming everything is automatically included at full value.
- Confusing actual cash value (ACV) policies with replacement cost value (RCV) policies — ACV factors in depreciation, which can significantly lower a payout.
Best Free Tools for Estimating Your Coverage Needs
Getting these calculations right doesn't require hiring an appraiser for every decision. A few free tools can help homeowners get a realistic starting point:
- Homeowners Insurance Calculator — estimate a reasonable dwelling coverage range based on your home's characteristics.
- Life Insurance Calculator and Term Life Insurance Calculator — useful for homeowners thinking about mortgage protection and estate planning alongside property insurance.
- Whole Life Insurance Calculator — for comparing long-term coverage strategies tied to homeownership and family planning.
- Reverse Mortgage Calculator — helpful for homeowners evaluating how home equity fits into their broader financial picture.
- Concrete Calculator — a practical way to estimate materials costs relevant to structural rebuild scenarios.
- Commercial Loan Calculator — for property owners weighing financing decisions connected to real estate improvements.
FreeCalculators.tools maintains a full library of free financial and planning calculators designed to help homeowners make informed, numbers-based decisions rather than relying on guesswork.
Future Trends in Homeowners Insurance and Property Valuation
The homeowners insurance space is shifting toward more precise, data-driven underwriting:
- AI-powered replacement cost estimators are increasingly able to factor in real-time construction material pricing and regional labor rates.
- Automated property valuation models are helping insurers and homeowners separate land value from structure value more accurately and instantly.
- Digital underwriting tools are reducing reliance on static, outdated coverage limits by flagging when a policy appears underinsured relative to current rebuild costs.
- Climate-driven risk modeling is increasingly influencing premiums in wildfire- and flood-prone regions, independent of land value itself.
As these tools mature, homeowners can expect more accurate, personalized dwelling coverage recommendations rather than one-size-fits-all estimates based on outdated appraisals.
Frequently Asked Questions
Does homeowners insurance cover land?
No. Homeowners insurance is built around dwelling and structure coverage, not land value. The land beneath your home retains its value independently of what happens to the structure, so it isn't part of a standard homeowners policy.
Why isn't land covered by homeowners insurance?
Land can't be damaged by covered perils like fire or wind the way a structure can, and it retains value after a loss. Insurers focus coverage on replacement cost for the physical structure instead.
Is land included in dwelling coverage?
No. Dwelling coverage (Coverage A) applies to the physical structure of your home, not the market value of the land it sits on.
Does replacement cost include land?
No. Replacement cost reflects the cost of materials and labor to rebuild your home, entirely separate from land value or market pricing.
Is homeowners insurance based on market value?
Generally not. Homeowners insurance is based on replacement cost — what it would take to rebuild the structure — rather than the property's overall market value, which includes land.
What happens to land after a house is destroyed?
The land remains the owner's property. Insurance pays for rebuilding costs based on dwelling coverage; the land itself was never insured because it wasn't at risk of being "lost."
How do I calculate the right dwelling coverage?
Base it on your home's square footage, construction materials, local labor and material costs, and any special features — not on your purchase price or market value. A dedicated calculator can help estimate a realistic figure.
Does expensive land increase homeowners insurance premiums?
Not directly. Premiums are more closely tied to the cost to rebuild the structure and regional risk factors (like wildfire or hurricane exposure) than to land value itself.
Is dwelling coverage the same as home value?
No. Home value includes land and market conditions; dwelling coverage strictly reflects rebuild cost for the structure.
Key Takeaways
- Land value exclusion means homeowners insurance generally does not cover the market value of the land your home sits on.
- Dwelling coverage (Coverage A) is based on replacement cost, not market value or purchase price.
- Market value and replacement cost are two different numbers, often significantly apart in high-demand real estate markets.
- After a total loss, the land remains yours — insurance pays to rebuild the structure, not to replace land value.
- Landscaping and outdoor property coverage varies by policy and is usually limited.
- Underinsurance is a common mistake caused by confusing property value with dwelling coverage needs.
- Free tools like a homeowners insurance calculator can help homeowners estimate realistic coverage amounts.
Expert Summary
Land value exclusion in homeowners insurance reflects a straightforward underwriting principle: insurers cover what can be damaged, not what retains value regardless of a loss. Dwelling coverage is calibrated to replacement cost — the price of materials and labor to rebuild a home — rather than to market value, which is heavily influenced by land, location, and demand. Homeowners who understand this distinction are better equipped to set accurate coverage limits, avoid underinsurance, and interpret their declarations page with confidence rather than assuming their policy should mirror their home's full sale price.
Conclusion
Understanding land value exclusion in homeowners insurance clears up one of the most common points of confusion for homeowners: why your coverage limit doesn't match your home's total market value. Land retains its worth regardless of what happens to the structure sitting on it, which is exactly why insurers focus dwelling coverage on replacement cost instead. By basing your coverage decisions on rebuild cost — not purchase price or market value — you can avoid underinsurance and make sure your policy actually protects what matters most: the physical home you'd need to rebuild.
If you'd like personalized help thinking through your coverage numbers, mortgage decisions, or broader financial planning, consider exploring what's available through FreeCalculators.tools, or reach out directly to talk through your specific situation.
Ready to get your numbers right? Don't leave your dwelling coverage to guesswork — Book a Seat with our planning resources and start using data-backed tools today. Explore the full FreeCalculators.tools homepage, learn more About Us, browse our full range of Services, or Contact Us with questions. Dive deeper into related topics on our Blogs page, including our guide on how much term life insurance you need in 2026. For your coverage calculations, start with the Homeowners Insurance Calculator, compare protection options with the Life Insurance Calculator, Term Life Insurance Calculator, and Whole Life Insurance Calculator. If you're also insuring a vehicle alongside your home, check the Car Insurance Calculator and Auto Insurance Calculator. Homeowners planning renovations may find the Concrete Calculator useful for rebuild estimates, while those weighing equity or financing options can use the Reverse Mortgage Calculator and Commercial Loan Calculator. Business owners managing property assets can also explore the Business Calculator, and everyday budgeting needs are covered by our simple Basic Calculator. Whatever your next step is, FreeCalculators.tools is here to help you plan with confidence.